
Sustainable Finance Policy
Responsible Lending
SinoPac Holdings understands the financial industry plays an important role in reducing global carbon emissions, as it controls the majority of the cash flows supporting the economy. SinoPac Holdings incorporates ESG factors into its risk assessment process and pays close attention to clients' understanding towards the risks and opportunities brought by climate change as well as its impact on financial performance, in order to take proactive countermeasures further.
Corporate Banking Lending
KYC and CDD Processes for Corporate Lending
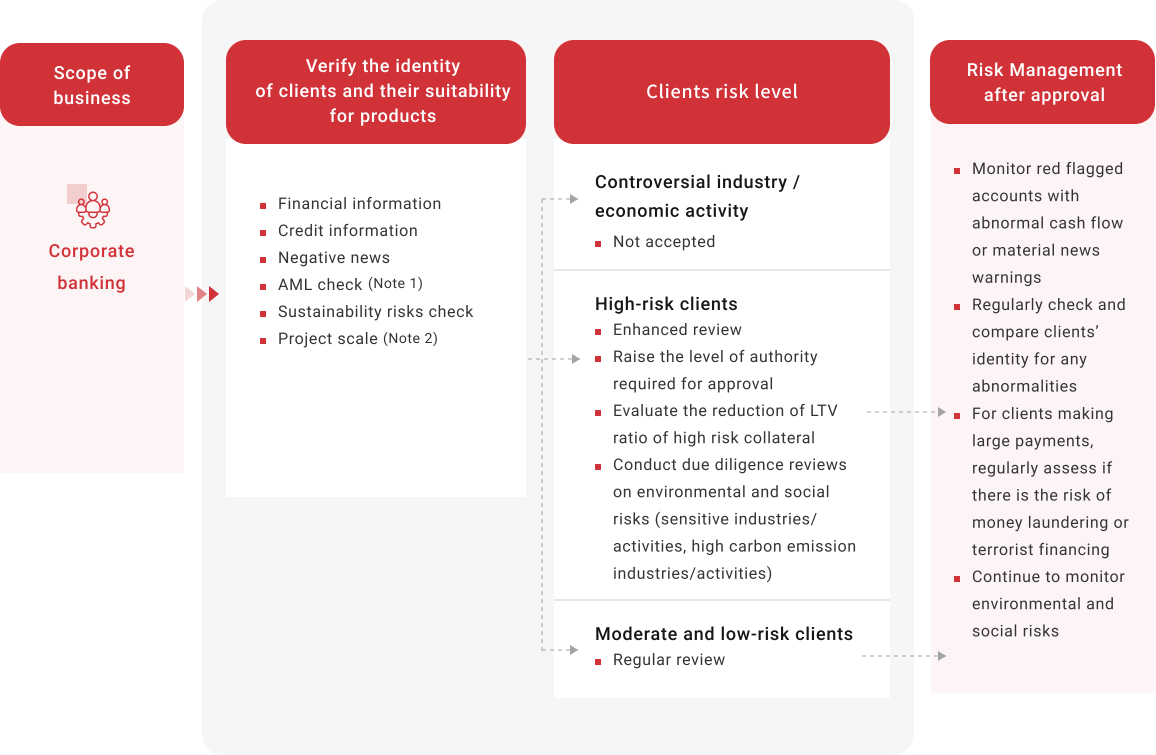
SinoPac Holdings incorporates ESG factors into its Know Your Customer (KYC) and Customer Due Diligence (CDD) procedures, and implements classified management of corporate banking clients, carrying out reviews and management operations by risk level.
 Note
- Please see SinoPac Holdings 2025 Sustainability Report section 2.2.2.3 Customer Due Diligence.
- For project finance cases of Bank SinoPac and King's Town Bank reaching NT$300 million or more (or equivalent in foreign currency totaling US$10 million or more), or project-related corporate loans, bridge loans, project-related refinancing, and project-related acquisition financing cases that meet certain conditions and amounts, as well as project finance financial advisory services, risk classification must be conducted in accordance with the Equator Principles.
- Bank SinoPac's corporate banking credit extension and lending process introduced the " ESG Disclosure Assessment ESG Checklist and Assessment Form," which applies to all cases (without restrictions on amount and fund usage), including project finance under US$10 million. The assessment form corresponds to IFC Performance Standards PS1–PS8 and complies with the climate change requirements of the Equator Principles.
Bank SinoPac and King’s Town Bank formulated management guidelines related to responsible lending, while Bank SinoPac (China) formulated working guidelines for green credit lending. When conducting corporate banking lending operations, they assessed the environmental, social, and governance performance of borrowing clients on a case-by-case basis, incorporated ESG factors in the credit extension procedures, and provided sustainable products such as green credits, social responsibility credits, and sustainability-linked loans for positive financing.
Bank SinoPac as an example, "Corporate Credit Risk Management Division" is the dedicated unit responsible for establishing guidelines relating to responsible lending and the EPs, and for planning a conducting ESG credit risk analysis. The Division continues to monitor trends in ESG risks of each industry and their impact on the Bank's operations. In terms of execution, front line corporate banking personnel are responsible for disclosing and specifying the ESG risks of clients. Corporate banking credit review personnel are then responsible for checking and reviewing the analysis of ESG factors in credit applications. Corporate banking and credit review personnel jointly complete due diligence of ESG risks.
Review process and engagement includes:
- Prohibit controversial industries: e.g., pornography, controversial arms.
- Carefully evaluate in Sensitive Industries/ enterprises / sensitive economic activities such as gambling, food safety concerns, harmful radioactive materials, genetic engineering non-medical or harmful to human development, non-bonded asbestos fiber and PCB manufacturing, oil and gas mining exploitation and wholesale, tobacco manufacturing related industries, tropical rainforest logging/driftnet manufacturing, fishing using driftnets, and high climate risk industries (including high carbon emission industries, etc.), they conduct due diligence and prudent assessments, and strengthened ESG risk analysis to serve as responses and strategies for credit reviews. If a client still fails to propose concrete response strategies (including avoidance, minimization, mitigation, and compensation) or relevant transition plans, they prudently evaluate whether to reduce or continue providing funds.
- Follow the business restrictions imposed by the “Decarbonization Policy” of SinoPac Holdings.
-
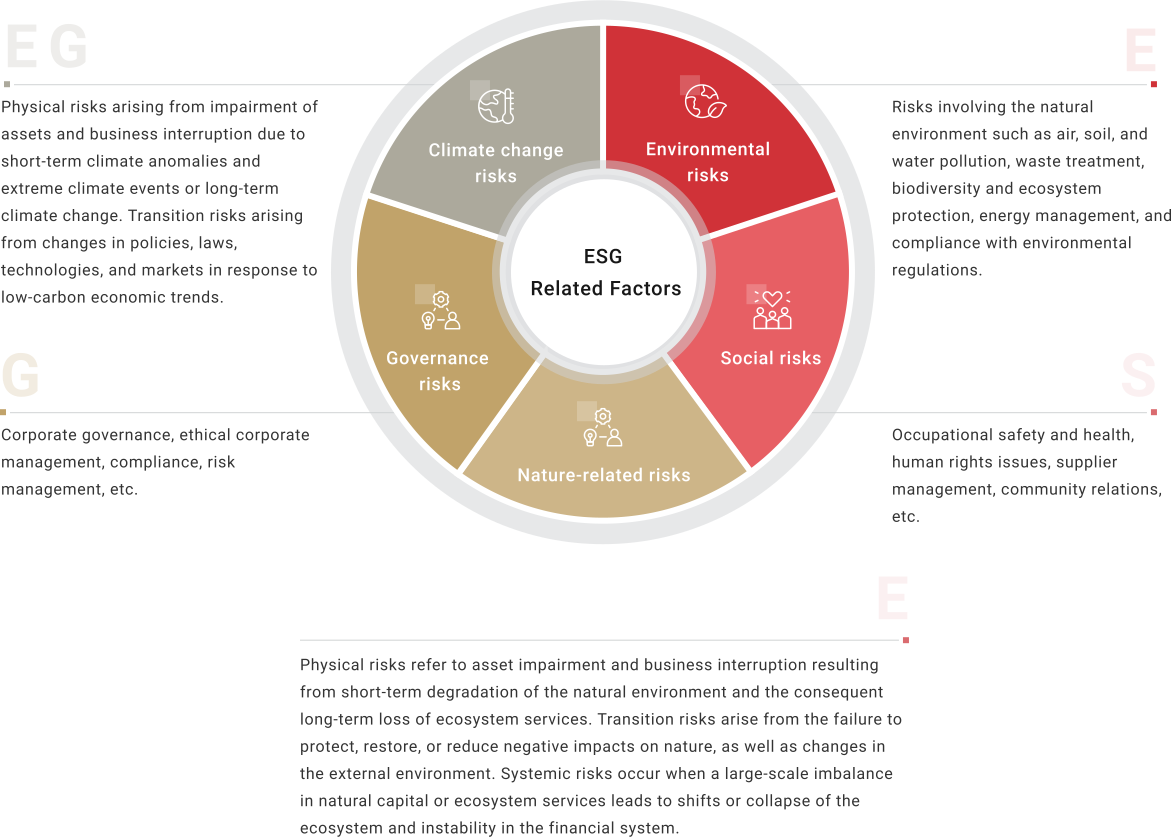
Incorporate ESG related factors, such as environmental, social, governance, and climate change risks etc., into the lending processes:
Post-Lending Management and Engagement
The banks continuously track whether clients fulfill their responsibilities regarding environmental protection, corporate integrity management, and social responsibility through regular reviews or post-lending early warning mechanisms. If signs of ESG risks or abnormal fund flows are detected in credit clients, the banks actively reach out to learn about the situation, assist the clients in proposing improvement plans and mitigation measures, and take necessary responsive actions depending on the specific circumstances of each case. The Company has enhanced ESG risk reviews for large project financing and continues to monitor environmental and social risks after approval. For details on incorporating ESG factors into corporate banking lending, please refer to the official website of SinoPac Holdings.
- Focus on whether clients assess and respond appropriately to the risks and opportunities of climate change and natural capital, whether they understand the impact of climate change and loss of biodiversity (including conservation of species, habitat preservation etc.) on their financial performance, and whether they have taken response measures.
- Communicates and collaborates with clients in industries with high climate risks (including industries with high carbon emissions) and advises them to provide data on GHG emission intensity and low carbon transition strategies, and invest in sustainable economic activities.
- Encourages clients to engage in socially responsible lending to resolve or mitigate specific social issues, or create positive impact on the society.
- Bank SinoPac directs funds to sustainable economic activities and encourages clients to refer to thefollow the "Taiwan Sustainable Taxonomy", and invests in transition lending.
Equator Principles
Bank SinoPac formally became a signatory to the Equator Principles (EPs) in February 2020. In the same year, Bank SinoPac established EPs related guidelines and operating procedures, completed EPs training sessions, and transitioned to EP4, strengthening the management of human rights risks and climate change risks in the credit analysis and lending process for project financing.
Bank SinoPac established a dedicated "Environmental and Social Risk Team" in November 2021, which serves as an internal consultant for assisting the risk assessment and review of EPs cases. Bank SinoPac also complies with EP4 and the eight Performance Standards of International Finance Corporation (IFC) and included climate change and biodiversity risks as necessary items for risk assessment. For high-risk cases, the team seeks assistance from a third-party external consultant according to the EPs. Bank SinoPac has also incorporated Equator Principles cases into the self-inspection items starting from December 2022 and a third party from head office regularly inspects the process of Equator Principles cases.
Since 2022, Bank SinoPac discloses the industry, risk category, and designated or non-designated country of project financing, number of cases involving environmental and social risks management, and whether or not an environmental and social risks assessment report prepared by independent third-party experts is provided on the official website of the Equator Principles Limited.
King's Town Bank signed the Equator Principles in December 2022, and promulgated the "KTB Equator Principles Financing Guidelines." When accepting corporate financing applications, the applicability of the Equator Principles must be determined based on the loan amount and purpose of each case. Bank SinoPac (China) established the Equator Principles Operating Manual to require reviews of large-scale project financing within its corporate banking lending business in accordance with relevant principles.
EPs Credit Analysis and Lending Process (Bank SinoPac as an example)

Retail Banking Lending
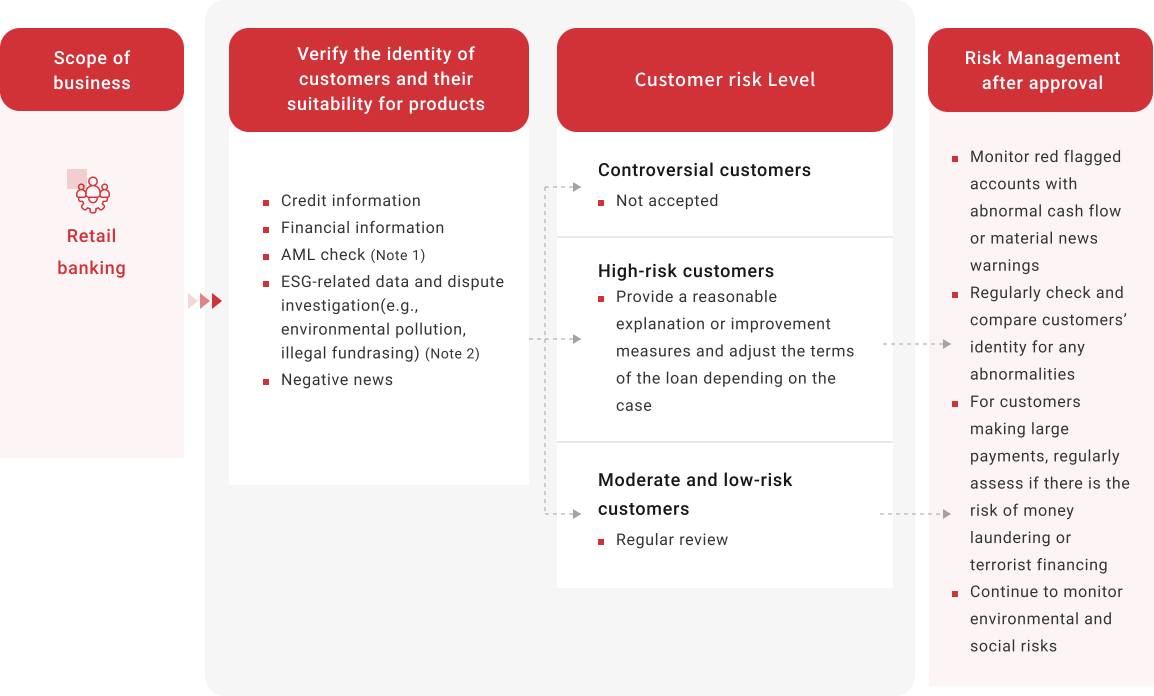
The subsidiary banks of SinoPac Holdings incorporated ESG factors in their retail banking businesses (including mortgage, motor vehicle loan, credit loan, and credit cards). When a new retail banking loan application is received, besides carrying out KYC and CDD mechanisms, the Company actively investigates the customers’ ESG related information and uses the ESG risk they may face for risk grading, appraisal, and adjustment of loan terms.
KYC and CDD Processes for Retail Banking Lending
 Note
- Please see SinoPac Holdings 2025 Sustainability Report section 2.2.2.3 Customer Due Diligence.
- The environmental and social factors incorporated into related ESG surveys include whether the collateral is located in areas with regulatory restrictions and flood-prone areas and whether customers are implicated in penalties for polluting the environment, money laundering and terrorist financing, and illegal fundraising.
Bank SinoPac as an example, the process starts with Know Your Customer (KYC) procedures, including identity verification, product suitability, and Customer Due Diligence (CDD). In addition to standard credit, financial, and anti-money laundering (AML) checks, Bank SinoPac assess key ESG (Environmental, Social, and Governance) factors—such as environmental violations and illegal fundraising—to identify major social risks.
Based on KYC, CDD, and ESG findings, customers are classified by money laundering risk: controversial, high, or moderate and low. Applications with significant ESG controversies are declined, and high-risk clients must provide explanations or corrective actions. After credit approval, we continuously monitor transactions, news, and ESG risks to ensure ongoing compliance with sustainability and regulatory standards, strengthening overall risk management.
Considering sustainability risks in the credit investigation and review process of the retail banking business
- In the mortgage review process, if the property is located in a restricted area or area prone to flood, debris flow, or soil liquefaction (with high physical climate risk), the application should be rejected during the appraisal review process if the collateral is not the target case. If the case should be taken due to special considerations, the loan-to-value should be lowered and enhance the level of case approval.
- Major earthquakes and natural disasters are taken into consideration when dividing the area where the property is located into grades A, B, and C, which are then used for valuation.
- In the process of reviewing corporate motor vehicle loan applications, the Company checks clients’ records and information on fines imposition due to severe pollution cases. If it is involved in such cases, Bank SinoPac requires the company to provide a reasonable explanation and improvement measures and will adjust the terms of the loan depending on the case.
Exclusion/Rejection conditions in the credit investigation and review process of the retail banking business
- The loan application of sanctioned parties, terrorists, or terrorist groups confirmed or investigated by foreign governments or international AML organizations, and individuals, corporate entities, and groups sanctioned under the Counter-Terrorism Financing Act, shall be rejected.
- During the credit investigation process, if the customer was found to have previously gained illegal profit from the sale of unlisted stocks, the application shall be rejected after verification.
- In the review process for corporate credit cards application, if the client was found to involve in illegal funds raising through online gambling, the application shall be rejected after verification.
- In the process of reviewing corporate motor vehicle loan applications, the Company checks clients’ records and information on fines imposition due to severe pollution cases. If it is involved in such cases and does not propose effective improvement measures, the case shall be rejected.
After approval, Bank SinoPac will examine whether retail credit products show any major warning signs or potential abnormalities based on customer or case indicators, and will regularly track customers' credit status and repayment performance to reduce overdue risk. Through practical actions, Bank SinoPac incorporates the potential risks of its credit products and the use of funds on social, environmental, and governance aspects into consideration.
If customers have any overdue payments, Bank SinoPac adopts different collection strategies based on the time payments are overdue. According to the debt negotiation mechanism set forth in the “The Statute for Consumer Debt Clearance” promulgated by the government, debtors who are unable to repay their loan for consumption, credit card or cash debt may submit an application to the bank for negotiation, and jointly formulate a feasible repayment plan with the bank. This approach helps people who have financial difficulties due to debt to have an opportunity to rebuild their life and economic status. For loans that cannot be collected, bad loans are regularly written off to maintain asset quality. When collection is outsourced, if the collection agency engages in improper conduct that is against the law or severely damages the Company's reputation, Bank SinoPac will initiate emergency response procedures.